
AI Acceleration is only Beginning for Private Equity Firms: Insights from the 2026 Citizens Private Equity CFO Conference
Key takeaways
- Artificial intelligence is becoming a strategic priority for private equity firms, influencing how investment teams evaluate opportunities, manage portfolio companies and scale operations.
- AI effectiveness depends on data quality and institutional knowledge. Firms with structured data, documented processes and accessible historical insights are better positioned to generate value from AI.
- Judgment, relationships and trust remain central to investing, even as AI expands access to information and accelerates analysis.
Few industries have had a closer view of the AI boom than private equity.
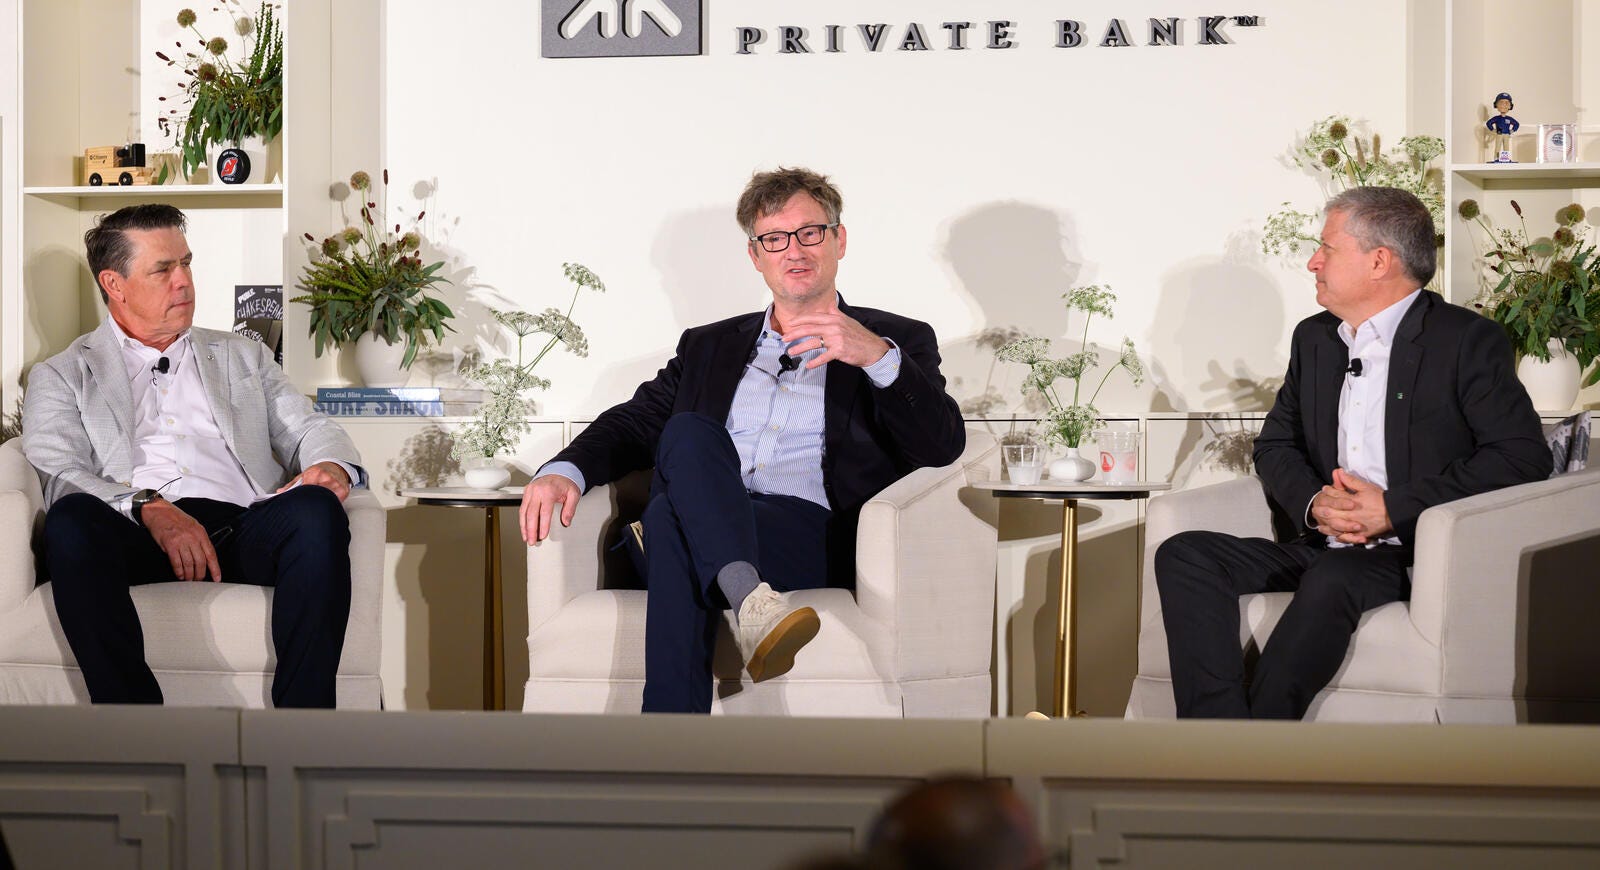
Investors evaluate AI companies directly and encounter AI as a dominant theme in fundraising across sectors. Against that backdrop, AI emerged as the defining topic at the 2026 Citizens Private Bank Private Equity CFO Conference, where the conversation turned inward. While private equity firms remain active investors in the AI ecosystem, they are also beginning to confront how AI will transform the way investment organizations themselves operate.
Dr. Ashby Monk, Executive and Research Director of the Stanford Research Initiative on Long-Term Investing, offered his insight on the pace of AI integration in private equity operations, noting that "our industry is a little safer than medical industry, legal industry, coding, because we actually don't write enough down," while cautioning that this period of insulation may be shorter than many expect.
Investment decisions continue to rely heavily on institutional knowledge, judgement and relationships that often reside outside structured systems. Those characteristics have slowed AI's ability to penetrate the core decision-making processes of many private equity firms. As expectations for productivity and data-driven insights continue to rise, however, firms face growing pressure to document value-add processes and establish governance frameworks that allow knowledge to be applied more broadly across the organization.
AI is changing the economics of growth
Expanding on a theme that surfaced repeatedly during the conference's AI discussion, Mark Lehmann, President of California Citizens Bank, pointed to both the scale of the opportunity and the speed of adoption. Lehmann observed that "this is a magnitude, in terms of urgency, we've never seen before." The current cycle extends beyond the emergence of new AI companies, altering the economics of building businesses in any sector.
For decades, startup growth often required expanding teams, adding infrastructure and raising additional capital to support scale. AI introduces the possibility that some businesses may achieve similar outcomes with leaner organizations and different operating models. As automation becomes more accessible and knowledge work becomes easier to augment, founders may be able to reach milestones that previously required significantly greater resources.
Those shifts have the potential to influence how quickly companies can scale and how much capital they require to do so. As private equity firms evaluate the opportunities AI creates within portfolio companies, they are also beginning to examine how the technology could alter long-standing assumptions in investment decision-making, particularly around operating leverage, workforce growth, value creation and the role investors play in helping businesses reach the next stage of development.
The conference discussions reflected both optimism and uncertainty. While the precise pace of adoption remains difficult to predict, participants broadly agreed that AI is creating a different set of possibilities than prior technology cycles, forcing investors to revisit assumptions that have underpinned startup and private equity investing for decades.
From data to intelligence
During the conference session, Dr. Monk framed AI readiness through a progression from data to information, knowledge and ultimately intelligence. "It's useful to understand this hierarchy of insight, which goes from data to information, to knowledge, to intelligence," he explained. Each layer depends on the quality of the one beneath it. Raw data becomes useful when it can be organized into reliable information. Information becomes more valuable when it is connected to context, experience and repeatable processes. Intelligence emerges when those inputs can support better decisions at greater speed and scale.
That progression exposes a practical challenge for many private equity firms. Investment organizations may hold significant amounts of data across deal pipelines, portfolio reporting, diligence materials, operating partner notes and investor communications, yet much of that material remains fragmented across systems and individual workflows. In that environment, AI has less to work with. The technology can identify patterns, summarize materials and accelerate analysis, but its output depends on the inputs available to it.
Cleaner data expands the range of problems AI can help solve. A firm with well-structured portfolio information, documented investment theses, consistent reporting practices and accessible historical context can begin to use AI for more valuable use cases. Those cases may include faster comparisons across opportunities, deeper portfolio-level analysis, more efficient knowledge transfer and better use of the judgment already embedded across the organization.
The next evolution of the investment firm
The conference panelists frequently cited the distinction between using AI to complete tasks and using AI to improve decision-making. For many of the CFOs in attendance, that distinction represented a pressing question facing their firms today: whether AI will remain primarily a productivity tool or evolve into infrastructure that improves how investment decisions are made.
Many of today's applications focus on summarization, research support, reporting and workflow automation. Those use cases can create meaningful efficiencies, but panelists suggested that the larger opportunity lies elsewhere.
Dr. Monk encouraged participants to think of AI as both a tool and an operating system. Over time, firms may develop systems capable of connecting information across funds, portfolio companies, investment memos, operating reviews and institutional experience. That broader view could help organizations identify patterns, risks and opportunities that would otherwise remain dispersed across teams and systems.
"The real power in the investment industry is when you realize something about your portfolio that you didn't know," Monk said. The firms that build those capabilities could develop more informed and consistent approaches to decision-making across the organization.
Judgment, relationships and trust
While conference participants acknowledged AI’s potential to expand access to information and accelerate analysis, the conversation repeatedly returned to the human elements of investing that remain difficult to systematize.
Assessing management teams, developing conviction and making decisions amid uncertainty require context, experience and judgment that extend beyond the information available in a dataset. Investing requires deciding which signals matter, weighing competing considerations and applying lessons learned across market cycles, portfolio situations and investment outcomes.
Relationships remain an equally important component of the investment process. Investors build partnerships with founders, management teams, limited partners and operating executives over many years. Capital allocation often involves assessments of credibility, alignment and trust that develop through direct interaction and experience. The discussion suggested that AI will continue to expand the amount of information and knowledge available to investment professionals. The application of that knowledge will remain in the purview of experienced professionals with sound judgment and strong relationships.
Final thoughts
The Citizens Private Equity CFO Conference has long served as a forum for discussing the forces driving the future of the industry. This year's conversation on AI highlighted how quickly those forces are changing. While firms continue to evaluate the technology's impact on portfolio companies, many of the industry's leading investors and operators are now turning their attention inward, asking how AI may improve the organizations and investment processes themselves.
Through events such as the Citizens Private Equity CFO Conference, Citizens Private Bank engages with private equity leaders on the trends influencing investment firms, portfolio companies and the broader private markets ecosystem. To learn more about the opportunities and challenges discussed at the conference, contact a Citizens Private Bank relationship manager.
For additional insights from the conference, read our 2026 Citizens Private Equity CFO Conference recap.
© Citizens Financial Group, Inc. All rights reserved. Citizens Bank, N.A. Member FDIC
Citizens Private Bank does not provide legal or tax advice. The information contained herein is for informational purposes only as a service to the public and is not legal advice or a substitute for legal counsel. You should do your own research and/or contact your own legal or tax advisor for assistance with questions you may have on the information contained herein.
Banking products are offered through Citizens Bank, N.A. ("CBNA"). For deposit products, Member FDIC.
Citizens Wealth Management (in certain instances d/b/a Citizens Private Wealth) is a division of Citizens Bank, N.A. ("Citizens"). Securities, insurance, brokerage services, and investment advisory services are offered by Citizens Securities, Inc. ("CSI"), a registered broker-dealer (Branch address: One Citizens Bank Way, Johnston RI 02919) and SEC registered investment adviser - Member FINRA/SIPC. Investment advisory services are also offered by Citizens Private Wealth, LLC ("CPW"), an SEC-registered investment adviser (see Form ADV Part 2A for details). CSI and CPW are affiliates of Citizens. Banking products and trust services are offered by Citizens. For deposit products, Member FDIC.
SECURITIES, INVESTMENTS AND INSURANCE PRODUCTS ARE SUBJECT TO RISK, INCLUDING PRINCIPAL AMOUNT INVESTED, AND ARE:
· NOT FDIC INSURED · NOT BANK GUARANTEED · NOT A DEPOSIT · NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY · MAY LOSE VALUE