
Financial Planning for Emerging Fund Managers: Lessons from the 2026 Citizens Private Bank Women in Venture Retreat
Key takeaways
- Emerging fund managers can benefit from coordinating fund formation, compensation, tax, estate and liquidity planning early, while options are still available.
- Pass-through income, carried interest and compensation structures can create tax obligations before cash is distributed, making proactive modeling important.
- Trust, transfer and retirement planning decisions should reflect each manager's personal goals, family circumstances, state of residence and fund-cycle timing
The wealth and tax-planning session at the Citizens Private Bank Women in Venture Conference, one of the conference's most anticipated panels, returned this year with an interactive conversation about the unique planning decisions facing emerging fund managers in venture capital.
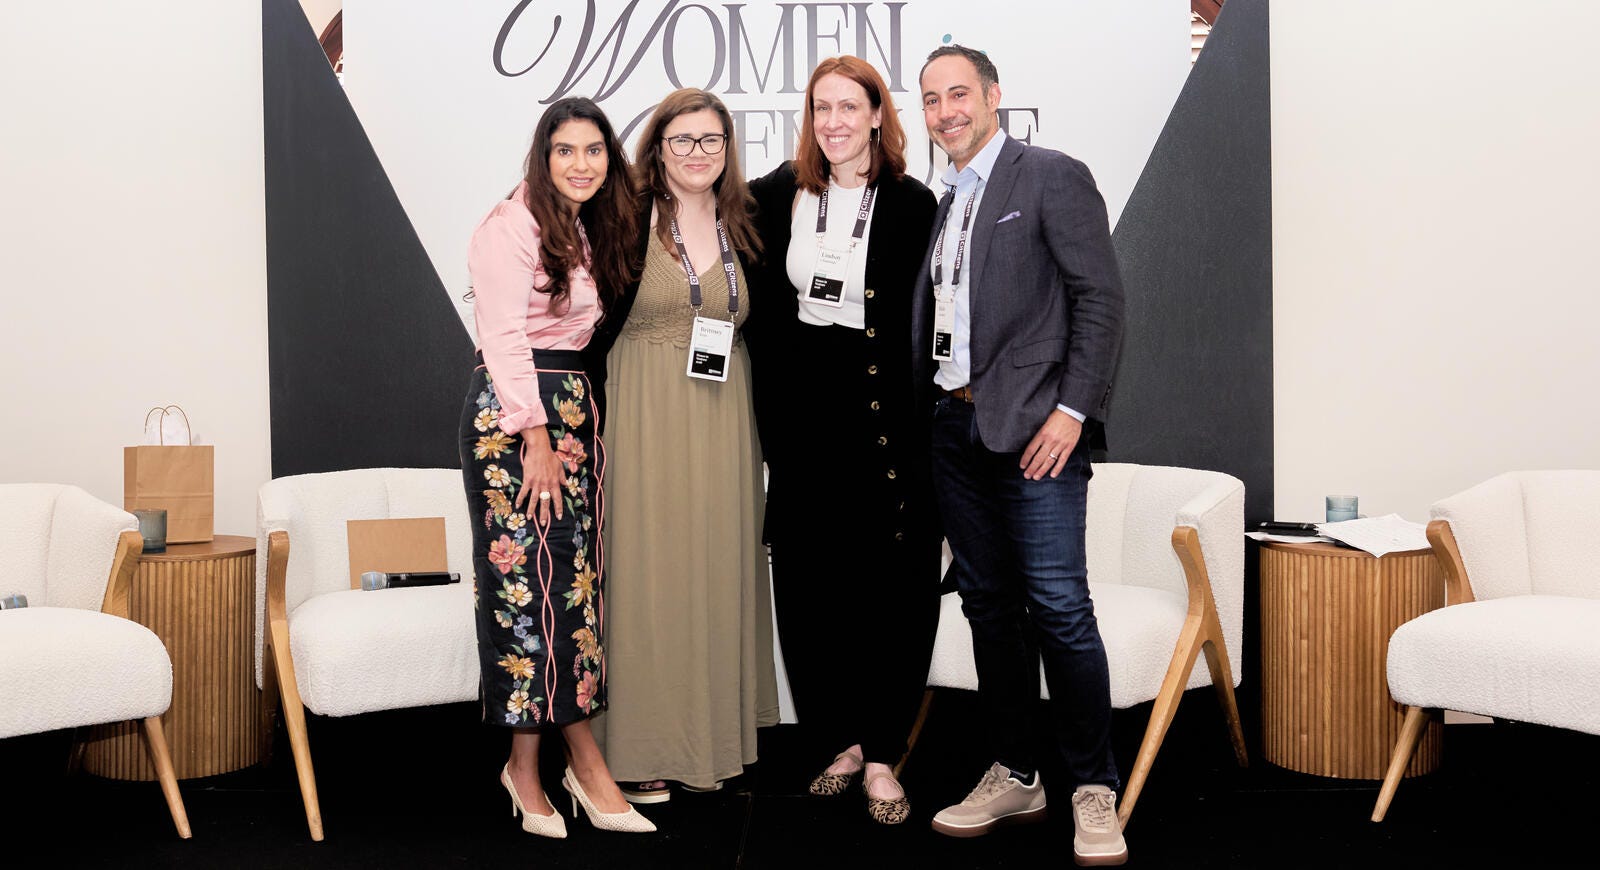
This year's panel brought together Rick Gordon, Senior Managing Director and Wealth Manager at Citizens Private Wealth; Jennifer Cuva, SVP and Regional Trust Director at Citizens Trust Company of Delaware; along with Lindsay Chamings of Andersen Tax and Brittney Kim of Frank Rimerman. Drawing on experience across wealth management, trust structuring, and fund-level tax advisory, the panel represented the range of highly specialized disciplines involved in these decisions.
The insights that emerged offered several practical applications for emerging managers, especially around decisions that impact fund structuring and the personal balance sheet. Here are the highlights from the conversation that can help new fund managers weigh the complex decisions of venture capital financial planning.
Getting experts involved at formation can prevent longer-term problems
When establishing a fund or entity, resist the temptation of relying on a friend with a law degree to draft the documents, unless fund formation is genuinely their practice area. Generalists may assemble language from unrelated deals and miss how the pieces interact, particularly there conciliation of tax allocations with tax distributions. Untangling those agreements after the fact can be difficult and costly.
New managers arriving from a corporate background face a related adjustment. Prior experience inside a corporate firm does not always translate to fund structure, and the panel encouraged new managers to learn how the entity works early, particularly around income and taxation.
Understanding the tax reality early can preserve optionality
The panel emphasized that fund and management entities are generally structured as pass-through entities, meaning a manager is taxed on an allocated share of income whether or not cash has been distributed. That reality limits the value of common timing strategies and shifts the focus toward legitimate deductions to reduce taxable income.
State considerations compound this, and timing can be unforgiving. Some elections must be made early in the year or the opportunity is lost. As with every topic discussed, the right approach is highly individual.
For carried interest, planning should start before crystallization
On the topic of carried interest, the panelists agreed that the most effective planning happens before the carry has meaningful value. Moving an interest into a trust early, while values are low, can allow future appreciation to grow outside the estate.
Valuation considerations for early-stage, illiquid interests can extend how far these planning tools go. For managers who want to retain some upside, there are structures that allow them to keep carry up to a defined threshold, then direct value above it elsewhere. These approaches add legal complexity and cost, which need to be weighed carefully.
Underlying these decisions is a question of intent: Where do these assets ultimately go, and when? Planning while children are young looks different from planning years later, and that time horizon should guide the approach.
Every compensation structure comes with tradeoffs
How a manager is paid is itself a planning decision, and each structure carries trade-offs. If a manager is open to it, there may be room to structure compensation more efficiently, but flexibility depends on what the partnership is willing to accommodate.
The choice between W-2 compensation and guaranteed payments carries specific implications for self-employment taxes and deductions. Managers negotiating a net figure should understand what they are actually taking home.
© Citizens Financial Group, Inc. All rights reserved. Citizens Bank, N.A. Member FDIC
Disclaimer: Citizens Securities, Inc. and Clarfeld Financial Advisors, LLC do not provide legal or tax advice. The information contained herein is for informational purposes only as a service to the public and is not legal advice or a substitute for legal counsel. You should do your own research and/or contact your own legal or tax advisor for assistance with questions you may have on the information contained herein.
Banking products are offered through Citizens Bank, N.A. ("CBNA"). For deposit products, Member FDIC.
All investing involves risk, including the risk of loss of principal. Investment risk exists with equity, fixed income, and other marketable securities. There is no assurance that any investment will meet its performance objectives or that losses will be avoided.
Citizens Wealth Management (in certain instances DBA Citizens Private Wealth) is a division of Citizens Bank, N.A. ("Citizens"). Securities, insurance, brokerage services, and investment advisory services offered by Citizens Securities, Inc. ("CSI"), a registered broker-dealer and SEC registered investment adviser - Member FINRA/SIPC. Investment advisory services may also be offered by Clarfeld Financial Advisors, LLC ("CFA"), an SEC registered investment adviser, or by unaffiliated members of FINRA and SIPC providing brokerage and custody services to CFA clients (see Form ADV for details). Insurance products may also be offered by Estate Preservation Services, LLC ("EPS") or an unaffiliated party. CSI, CFA and EPS are affiliates of Citizens. Banking products and trust services offered by Citizens.
SECURITIES, INVESTMENTS AND INSURANCE PRODUCTS ARE SUBJECT TO RISK, INCLUDING PRINCIPAL AMOUNT INVESTED, AND ARE:
· NOT FDIC INSURED · NOT BANK GUARANTEED · NOT A DEPOSIT · NOT INSURED BY ANY FEDERAL GOVERNMENT AGENCY · MAY LOSE VALUE