
How to win a home in a competitive market
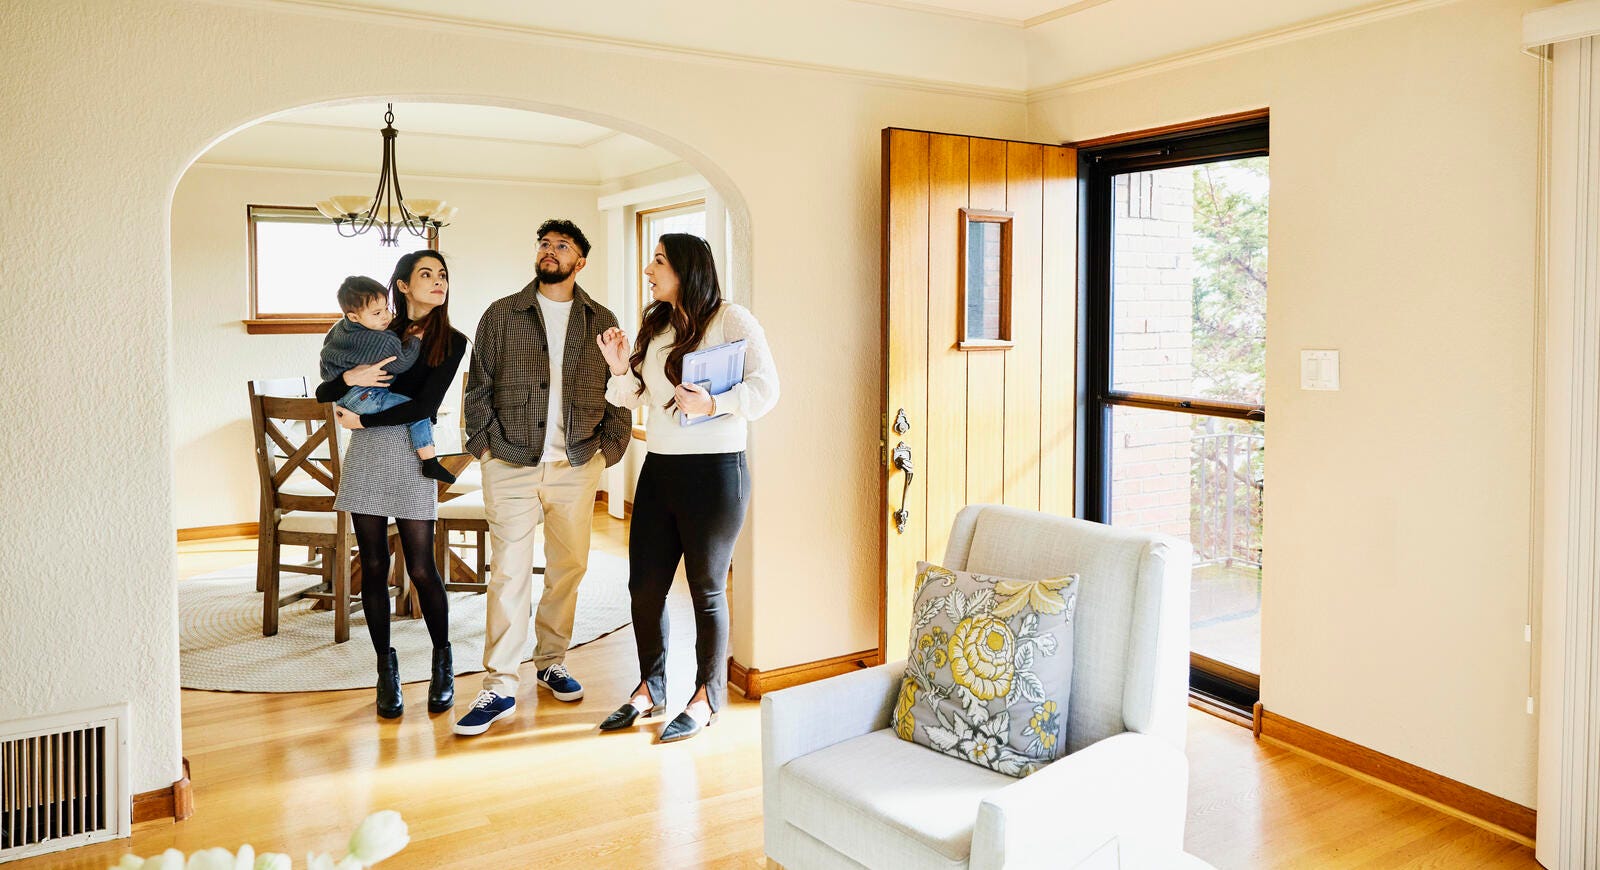
To win the bid for a home in a competitive market, your offer must convey that you're a serious buyer and that the sale will actually close. Understand what you can afford and obtain verified mortgage approval first. Your purchase offer should include clear terms, a price that's aligned with the market and a convenient closing date.
Key takeaways
- Sellers may consider an offer with verified preapproval as being nearly equivalent to a cash offer, which can help your bid stand out.
- Knowing your maximum bid before making an offer helps you know when to walk away if there are other bidders or you are bidding on emotion.
- Sellers may view offers with fewer contingencies or requests more favorably since they increase the likelihood that the home will close on schedule.
- Using comparables to estimate a home's market value helps you structure a bid that reflects its actual worth.
Buying a home in a competitive market can feel stressful and exhausting. Once you've found a house that meets your needs, you have to make a quick offer before other buyers place theirs. If multiple offers are in play, you might get outbid and have to start your home search all over.
Fortunately, winning in a crowded market has less to do with offering the highest amount and more to do with the quality of the offer you present. Explore the steps you need to take to bring a strong offer to the table and increase your chances of securing the home of your dreams.
The competitive buyer's checklist: Steps to win a home
To win a home in a competitive market, you need a strategy. The right approach can help your offer stand out and increase your chances of closing the deal.
1. Know your full financial position before you tour
Before you tour your first home, you need to understand what you can actually afford. However, don't just look at the list price or closing costs. Also consider the ongoing costs of homeownership, including:
- Property taxes
- Maintenance
- Homeowners insurance
- Utilities
- HOA fees (if applicable)
A lender may approve more than what your budget can absorb. Understanding the numbers before you begin helps you know your limit when you have to make a quick decision or when emotions are high.
Before making an offer, calculate your debt-to-income (DTI) ratio to help determine whether you can comfortably afford the mortgage payment. You should also evaluate how much cash you'll have remaining after your down payment and closing costs. Knowing your walk-away number before bidding can help you stay within your budget and avoid overextending yourself in a competitive market.
2. Secure a verified preapproval, not just prequalification
Obtaining verified mortgage preapproval helps you move quickly when you find the right home. Most of the paperwork and verification will already be completed, which may give you a competitive edge.
Mortgage prequalification and preapproval aren't the same. Prequalification is an estimate of what you qualify to borrow based on self-reported financial information. To obtain preapproval, your lender will verify your income and assets and check your credit.
In a competitive market, you may need more than standard preapproval. Sellers may view a fully underwritten preapproval nearly as strongly as a cash bid, helping your offer stand out.
Citizens preapproval letters are valid for 60 to 90 days. Be sure to get mortgage preapproval close to when you plan to start house hunting, so you have enough time to find a home and make an offer.
3. Build your offer around seller certainty and price
When considering offers, sellers look at both the offer price and the certainty of closing. They may view a higher-priced offer with weak financing as risky and reject it. However, they may accept a slightly lower offer with strong financing and fewer contingencies because it has a better chance of closing.
An offer may signal that the deal will close when it includes:
- Verified financing: Your income, assets and credit have already been checked, and the lender has agreed to loan a certain amount.
- Strong earnest money deposit: A higher good-faith deposit tells sellers you're serious about buying.
- Clean terms: Some contingencies or requests could slow the closing.
- Seller-aligned closing timeline: The proposed closing date is convenient for the seller.
According to Redfin, 71% of real estate agents say offering fewer contingencies is the most effective way to strengthen your offer. Having strong financing ranks in the top three.
4. Price strategically using comparables
Your offer should reflect the market value of the home. You can determine what a home is worth by looking up what similar homes in the area sold for in the past 90 days. These homes are often referred to as comparables or "comps."
The list price for a home is a starting point and not a ceiling. If you know there will be multiple offers, you could include an escalation clause in your offer that automatically increases your bid in increments up to a capped amount. However, this exposes your maximum offer to the seller, and you may not want to negotiate just the price.
Establish your walk-away price before submitting an offer. If you don't know your limit, you could become emotionally attached to the home and offer more than you otherwise would. Emotional overbidding is the single most common source of regret after buying a home.
5. Handle contingencies with precision
A contingency is a clause in your offer that requires the seller to meet a certain condition. It's a way to manage risk. If the condition isn't met, the contingency may allow you to renegotiate the deal or back out of it.
Not all contingencies offer the same level of protection, and you may choose not to include certain ones based on your financial situation. Common contingencies include:
- Inspection contingency: The home inspection must not reveal anything that would require costly repairs.
- Financing contingency: The deal depends on securing financing. It may be redundant if you have strong verified approval.
- Appraisal contingency: You're protected if the home appraises for less than the purchase price. Waiving it could strain your finances if you don't have sufficient reserves to cover the gap.
Obtaining information early may allow you to forgo certain contingencies. For example, a pre-offer inspection may reveal that a home is in good condition, allowing you to waive the inspection contingency.
6. Protect your long-term financial position when you win
Winning the bid doesn't mean you've reached the finish line. After the purchase agreement has been signed, the home is officially under contract. You can then focus on making sure the mortgage is structured so it actually builds wealth and it isn't just another debt payment.
Many people focus on getting the best mortgage rate. However, other factors, like the term, closing costs and whether the interest rate is fixed or variable, can affect your payment, how quickly you build equity and the total interest you pay over the life of the loan.
How you structure your mortgage also affects whether the seller sees your offer as a near-cash equivalent. A verified preapproval and ensuring you have sufficient room in your finances for the mortgage payment and a potential appraisal gap can increase the likelihood of closing without issues.
Winning the home is the beginning, not the end
Assessing your financial position before you even start looking at homes can help you make stronger offers. It could mean the difference between winning the bid on a home that truly meets your needs or accepting a compromise. Knowing the numbers up front also helps you structure your mortgage so it aligns with your long-term financial plans.
Ready to take the next step?
Buying a home is one of life's most important financial decisions. That's why thousands of homebuyers turn to Citizens for personalized guidance, competitive mortgage solutions, and support every step of the way. To learn more about our mortgage solutions, please call 888-514-2300, visit us online, or find a Citizens Loan Officer.
Related topics
How to buy a house: A step-by-step guide to home buying
Buying a home doesn't have to be stressful if you take it one step at a time. Discover how the process works from start to finish.
First-time home buyer tips
Buying a home for the first time can be intimidating. Check out first-time homebuyer tips for how to buy a house.
How to improve your credit score before buying a home
Learn some practical ways to improve your credit score to qualify for a mortgage with a better rate.
© Citizens Financial Group, Inc. All rights reserved. Citizens Bank, N.A. Member FDIC
Mortgages are offered and originated by Citizens Bank, N.A. (NMLS ID# 433960)
Disclaimer: The information contained herein is for informational purposes only as a service to the public and is not legal advice or a substitute for legal counsel. You should do your own research and/or contact your own legal or tax advisor for assistance with questions you may have on the information contained herein.
