
Using your Massachusetts home's equity to finance coastal investment properties
Key takeaways
- A HELOC on your primary home can help fund an investment property in coastal Massachusetts.
- You can use funds for a down payment, renovations, or other property-related expenses.
- During the draw period, you may be able to make interest-only payments on the amount you use.
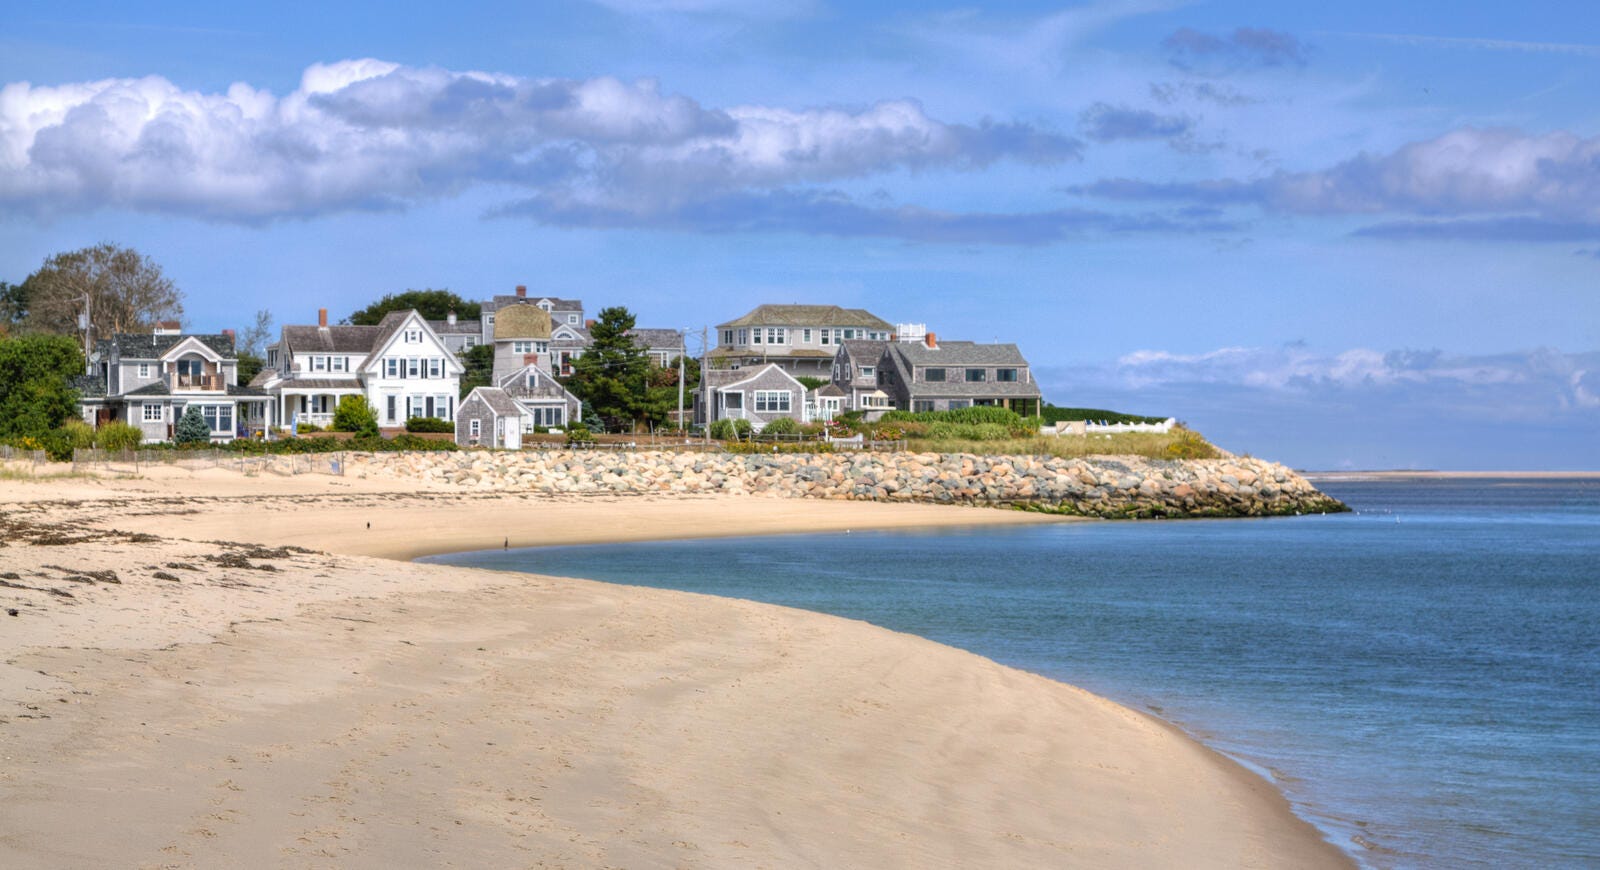
The Massachusetts coast remains a popular destination for both travelers and real estate investors. From Cape Cod to Martha's Vineyard and Nantucket, these markets continue to attract demand for their natural beauty, seasonal appeal, and strong rental potential.
If you're considering a coastal investment property in Massachusetts, a home equity line of credit (HELOC) can provide flexible access to funds. Understanding how a HELOC works and what lenders require can help you prepare to move forward when the right opportunity comes along.
What is a HELOC for an investment property purchase?
A home equity line of credit (HELOC) is a revolving line of credit backed by the equity in your home. It works similarly to a credit card, allowing you to borrow funds as needed up to a set limit.
When using a HELOC for an investment property, you can:
- Open the line of credit before you begin your property search
- Draw funds for a down payment or other upfront costs
- Use funds for renovations or ongoing expenses
- Repay what you borrow and reuse available credit over time
During the draw period, you may be able to make interest-only payments on the amount you borrow. After the draw period ends, you enter the repayment period and begin paying both principal and interest.
While some lenders may offer lines of credit on investment properties, they may come with higher rates since they are generally considered higher risk.
Massachusetts HELOC requirements and process
HELOC requirements in Massachusetts are similar to other home equity products. While specific criteria can vary by lender, most borrowers need to meet a few key requirements. The application process typically includes a home appraisal to determine your property value and available equity.
Home equity
To qualify for a HELOC, you’ll generally need at least 15% to 20% equity in your home. In most cases, your total loan-to-value ratio should not exceed 80% to 85%.
Credit score
A credit score of 680 or higher is often preferred, though some lenders may consider scores as low as 620 depending on your overall financial profile.
Debt-to-income ratio (DTI)
Your DTI compares your monthly debt payments to your income. Many lenders allow DTIs up to around 55%, depending on your financial situation.
Income and financial documentation
Lenders will verify your income and financial stability to ensure you can repay what you borrow. This typically includes reviewing your overall financial profile and supporting documentation.
Benefits for Massachusetts real estate investors
A HELOC can offer flexibility for real estate investors looking to finance opportunities in Massachusetts.
- Flexible access to funds
You can draw funds as needed for a down payment, renovations, or other property-related expenses. - Potentially lower borrowing costs
Because a HELOC is secured by your home, rates may be lower than some other financing options. - Upfront cost considerations
Costs can vary by lender. Some HELOC products may offer reduced or no application or closing costs.1 For example, a Citizens HELOC has no application fees or closing costs, which may help reduce initial borrowing expenses. - Ongoing access to capital
As you repay what you borrow, your available credit replenishes, allowing you to reuse funds for future investments or property improvements.
Financial considerations for investment properties
When using a HELOC to help finance an investment property, it's important to evaluate your overall financial picture. Consider your expected rental income, ongoing expenses, and ability to manage payments across both properties.
Because HELOCs typically have variable interest rates, your monthly payments may change over time. Planning for different scenarios—including slower rental periods or higher rates—can help you manage risk more effectively.
Prime Massachusetts investment markets
Where should you buy an investment property? The location you select can impact the purchase price and the rental demand. Local regulations can also vary, which may affect how you operate the property.
The three prime Massachusetts investment markets include:
Cape Cod
Cape Cod is a well-known New England destination with strong demand for short-term rentals. The tourist season typically runs from late spring through early fall, with summer often being the busiest period. Property values have generally remained strong due to zoning restrictions, environmental regulations, and limited land availability.
Martha's Vineyard and Nantucket
Martha’s Vineyard and Nantucket are high-value housing markets where homes and rentals often command premium prices. Inventory may be limited due to strong demand and restrictive zoning or environmental protections. In some cases, local approvals may be required for certain types of rentals.
Mainland Massachusetts
Mainland Massachusetts includes a range of different market types. Consider these areas as you narrow your search:
- Greater Boston and suburban markets: Urban-adjacent communities like the Boston suburbs may offer steady year-round rental demand and access to major employment centers.
- College towns and academic hubs: Markets near universities can provide consistent tenant demand, especially with longer lease cycles.
- Coastal and South Shore/South Coast communities: Emerging coastal cities and towns — like Plymouth, New Bedford and Salem — may offer investment opportunities that are closer to year-round amenities and may be more affordable than peak vacation markets.
How to get a HELOC for a Massachusetts coastal investment property
Before you start: prepare your financing strategy
- Research rental demand and pricing in your target area.
- Confirm zoning and short-term rental rules.
- Open a HELOC early so funds are available when you need them.
Opening a HELOC in advance can help ensure funds are available when you're ready to move forward on a property.
If approved, HELOC funds can be drawn through online transfers or by making a wire transfer for the down payment. For ongoing property maintenance, smaller amounts may be accessed by writing checks, using a linked debit card or drawing cash at a branch, depending on the lender, with some lenders such as Citizens offering convenient digital tools to help manage your line of credit.
Potential risks to consider
What to consider before using a HELOC for an investment property
Before using a HELOC, consider your ability to manage multiple properties, your tolerance for variable payments, and whether your expected rental income can support the additional debt.
Reduce risk when using a HELOC for an investment property
A rental property can be a good investment, but it’s not risk-free. Changing market conditions can affect property values and rental demand, and HELOCs typically have variable interest rates during the draw period—so your payment may rise or fall based on broader rate movements.
- Plan for higher potential payments by maintaining a financial reserve and avoiding using your full available credit line.
- Evaluate rental income stability and local market conditions to help support more sustainable borrowing.
- Account for seasonal cash flow: slower periods can make you feel over-leveraged, so a reserve fund can help you cover payments when rental income dips.
- Plan for property management and repairs. If you hire a property manager, costs may run about 15–30% of your gross rental revenue.
Finance your Massachusetts coastal investment property today
Buying an investment property may be more achievable than you think. A HELOC can help you cover the down payment and other costs at a rate that's often lower than other financing options. It can help you move quickly when the right opportunity comes along.
Ready to take the next step? Get your personalized HELOC rate today and see how easy it is to get started.
Related topics
Tips for investment property
Thinking about buying an investment property? Ask yourself these questions to see if it’s worth it.
Is a vacation home a good investment?
A vacation home is a great way to spend time with family and earn rental income. Discover why buying one might be a good investment.
5 smart things to do with a HELOC
The equity in your home is a valuable asset. Learn how to tap into your equity and explore common ways to use it.
© Citizens Financial Group, Inc. All rights reserved. Citizens Bank, N.A. Member FDIC
1 Variable Annual Percentage Rate: Variable Annual Percentage Rate ("APR") based on The Wall Street Journal Prime Rate ( Prime ) published on the last business day of the month, (6.75% APR as of 12/31/2025). Maximum APR 21%. Minimum APR 2.50%. Our best rate, including all rate discounts, cannot be lower than 2.50% APR. Eligible properties include owner-occupied 1-to 4-family properties, condominiums and second/vacation homes. Ineligible properties include, but are not limited to: investment property (defined as non-owner-occupied property), a co-op, mobile home or manufactured housing. Property must be located in AL, AR, CT, DC, DE, FL, GA, IA, IL, IN, KY, MA, MD, ME, MI, MN, NC, NE, NH, NJ, NY, OH, OK, PA, RI, SC, SD, TN, VA or VT. Rate and terms are subject to change and credit approval. Home equity lines of credit are available in first or second lien positions. Not available for homes currently for sale. Homes previously listed for sale must be off the market for at least 90 days prior to application. Property insurance required. Flood insurance may be required. Citizens offers Home Equity Lines of Credit as low as $17,500, but terms may vary. No annual fee for the first year, then $50 per year thereafter during the draw period. The Annual Fee is waived for the Citizens Home Equity Line of Credit if you have a Citizens Private Client™, Citizens Private Bank™ or Citizens Quest® Checking account open and active at the anniversary of your Credit Line when the Annual Fee would be assessed. If you do not meet this requirement, the Annual Fee of $50 will be charged to your Credit Line Account.
Home Equity Lines of Credit are offered and originated by Citizens Bank, N.A. (NMLS ID#433960)
Disclaimer: The information contained herein is for informational purposes only as a service to the public and is not legal advice or a substitute for legal counsel. You should do your own research and/or contact your own legal or tax advisor for assistance with questions you may have on the information contained herein.
